Part 4 of 15Institutional Trading
@AbePublished 6 min read

Fetching the page
Education · Analysis
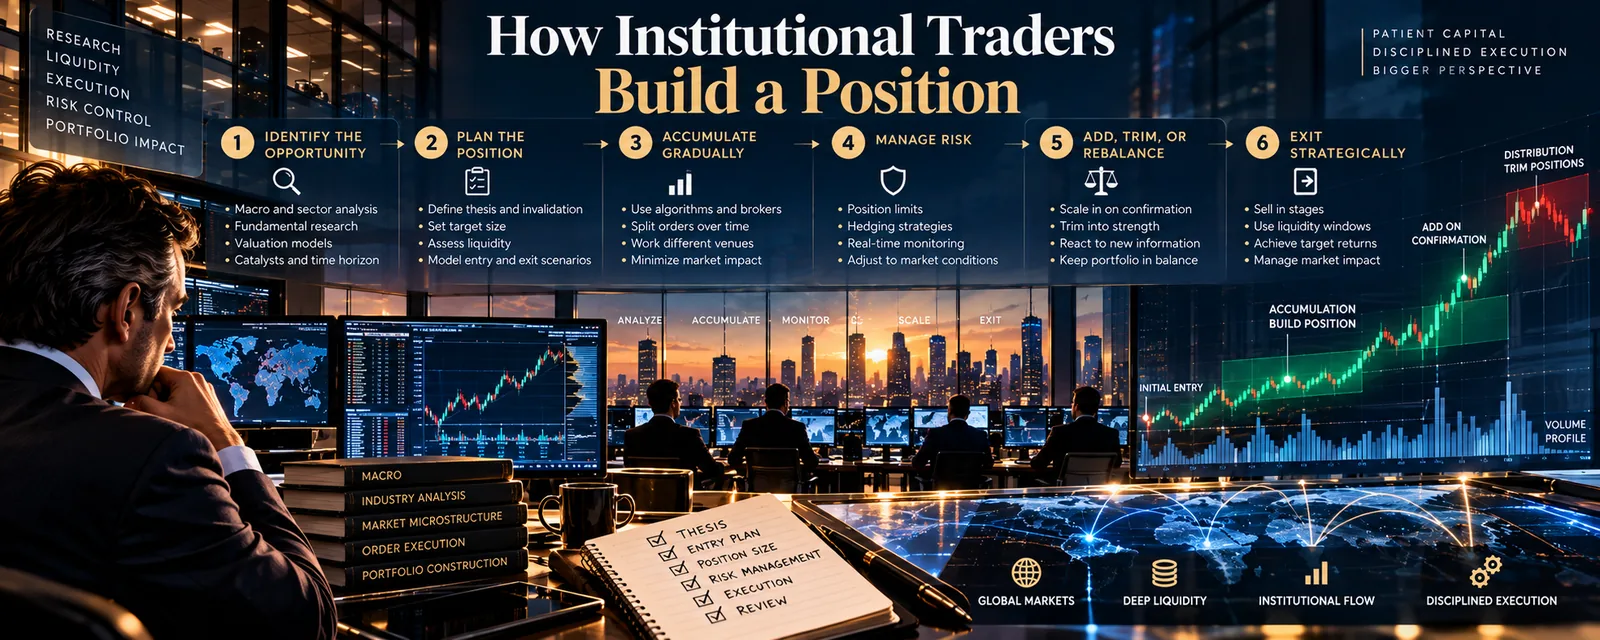
For a large order, entry is a sequence of decisions. Institutions often build positions in stages to manage market impact, timing uncertainty and the risk committed to an idea.
Part 4 of 15Institutional Trading
@AbePublished 6 min read
Scaling entries and exits within a defined risk budget
For a large order, entry is a sequence of decisions. Institutions often build positions in stages to manage market impact, timing uncertainty and the risk committed to an idea.
Desk insight. An addition must fit the whole idea’s risk budget. Open profit is not protection against a gap.
Retail trading culture is built around the single perfect entry. One click, full size, stop and target attached. Professionals treat entry as a process that may run for hours, days or weeks.
There are two reasons, and only one is about size.
The first reason is mechanical. Buying a large stake at once can move the price against the fund. Spreading execution may reduce impact and information leakage, although delay can make the final price worse.
The second applies to every account. Nobody knows the exact turning point. A full-size entry at one price is a bet on timing as well as direction. Staging the entry separates the two.
Before the first order, the trader knows the maximum position and the maximum loss on the whole idea. This is the budget.
Everything that follows is a way of spending that budget. Adding to a position never means adding to the budget. This is the line between scaling in and averaging down.
An unplanned addition to a losing position can enlarge the loss. In a disciplined scaling plan, each addition is assessed against the original risk budget. The planned loss at the stop is a limit for sizing, not a guarantee of the eventual fill.
Many traders open with a fraction of the planned size, often a quarter or a third. The purpose is partly information.
A live position sharpens attention. It shows how the market trades around the level, how deep the liquidity is, and whether the idea feels as good with money on it. If the trade fails here, the loss is small.
Some funds call this a tracking position. It keeps the idea on the screen and in the risk report without committing the book.
There are two honest ways to grow a position, and they suit different trades.
Adding into weakness. Used by value-minded investors who have a firm view of what something is worth. They place orders at successively better prices inside a zone. The plan assumes they will be early, so the first buy is small and the largest buys sit lower.
This requires an explicit invalidation condition and a cap on total exposure. Without them, adding at lower prices can become an open-ended commitment to a failing thesis.
Adding into strength. Used by trend and macro traders. The first entry is small. More is added only after the market confirms the idea, for instance by breaking a level or holding a retest.
Each add is paid for by open profit on the earlier pieces. The stop on the whole position is moved up as size grows, so the total risk stays flat or shrinks. This is often called pyramiding.
The average entry price is higher when a long position is built into strength. Full size is reached only after some confirmation, but whether that improves the win rate or return depends on the strategy and costs.
Large positions are often split in two. A core is held for the main thesis and left alone. A smaller trading portion is bought and sold around it as price swings.
This solves a psychological problem. A trader who wants to act can act with the trading piece, without disturbing the core. It also harvests some of the volatility along the way.
Institutions may also scale by time. A fund could choose to buy over ten trading days rather than commit at once. This spreads timing exposure; it does not guarantee a better price.
It avoids the regret of buying everything on the worst day. It also forces the idea to survive a few weeks of news before it reaches full size.
Exits are staged too. Part of the position comes off at the first target. This banks profit and makes the rest easier to hold.
The remainder is managed with a trailing stop or a thesis-based exit. Large funds need this for liquidity reasons. Small traders benefit because it removes the all-or-nothing decision at the top.
There is a cost. Scaling out reduces the profit on the trades that run furthest. It is a trade-off between total return and the ability to stick to the plan.
Take an account of 10,000 with a risk budget of 1 percent, or 100, on one idea. The trader wants to buy a breakout and add on a successful retest.
Illustrative staged position with a 100 risk budget
| Stage | Action | Size | Stop for whole position | Planned risk at stop |
|---|---|---|---|---|
| 1 | Buy the breakout | One third | Below the breakout base | About 35 |
| 2 | Add on the retest holding | One third | Raised to below the retest low | About 50 |
| 3 | Add on a new high | One third | Raised to the first entry price | About 40 |
| 4 | First target reached | Sell one third | Trail below the latest swing low | Profit protected at stop level* |
*Stop-level arithmetic excludes gaps, slippage and costs.
The figures are illustrative risk snapshots, not a fully specified price-and-quantity model. Planned risk stays below the original 100 as size rises and stops move. Gaps, slippage and costs can still make realised losses larger.
Key takeaway. Staging a position gives the trader several decision points. Each addition needs a reason: improving evidence, an acceptable price, or a pre-agreed execution schedule.
The method is available to anyone. The discipline is in setting the total risk first and never letting an add increase it.
Part 4 of 15 in the series Institutional Trading. Next: Why Professionals Think in Probabilities, Not Predictions.
Independent educational commentary, not investment advice. References to firms do not imply affiliation or endorsement. Figures in examples illustrate a method, not a recommended allocation or a promised outcome. Trading leveraged products carries a high risk of loss.
 AnalysisEducationTrade Like a Desk, Not Like a GamblerThe same entry can belong to a disciplined trading business or an impulsive bet. The difference sits around the order: a mandate, a repeatable setup, a risk budget and an honest review.@Abe5 min read
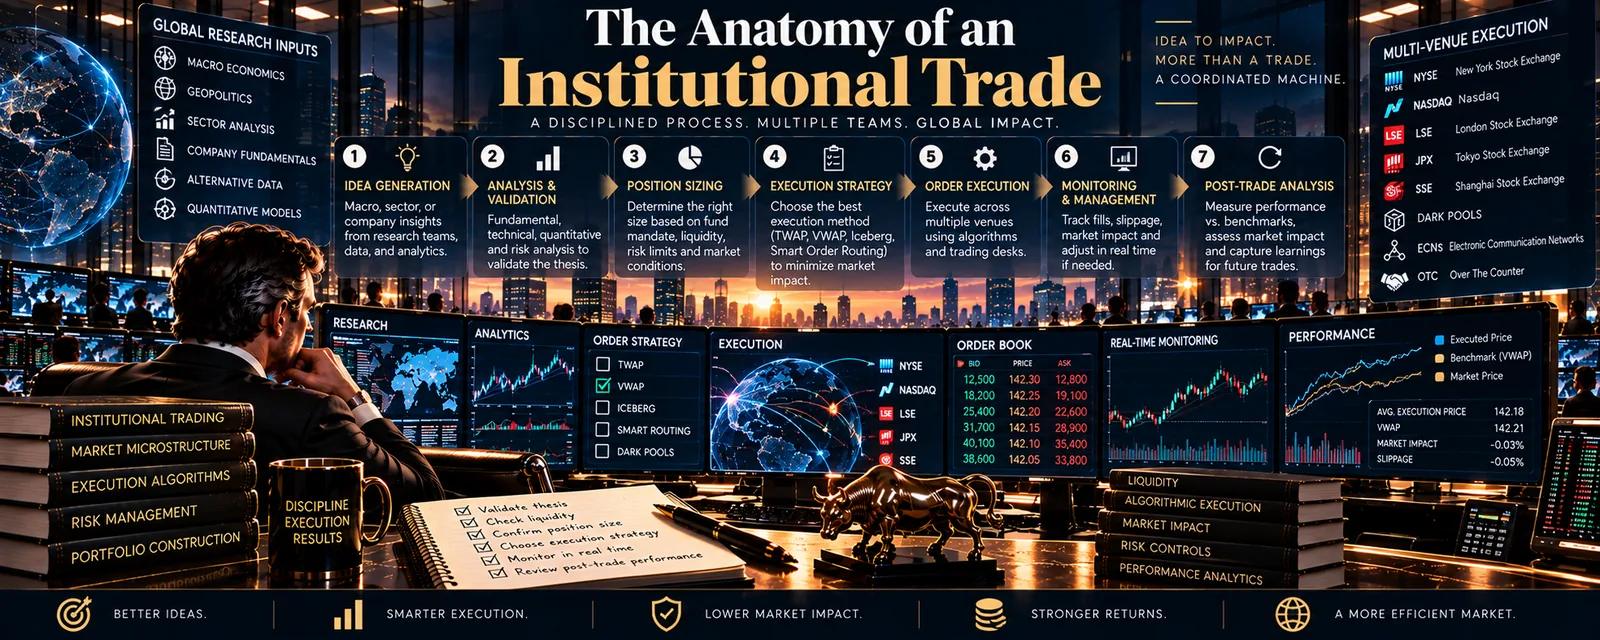 AnalysisEducationThe Anatomy of an Institutional TradeA trade starts long before the order and ends after the exit. This seven-stage framework follows an institutional idea through research, instrument choice, risk approval, execution, management and review.@Abe6 min read
 AnalysisEducationHow Goldman Sachs Thinks About RiskThe first question in institutional trading is how much can be lost, how quickly, and who will act. Goldman Sachs offers a useful lens on that discipline: risk is measured, challenged and escalated throughout the life of a position.@Abe5 min read
A short note from a GIO4X desk, filed under Education. It explains; it does not forecast and it does not tell you to trade. GIO4X is a broker and earns money when clients trade.
Editorial standardshttps://www.gio4x.com/intelligence/blog/how-institutional-traders-build-a-position
Printed from gio4x.com.