Part 3 of 15Institutional Trading
@AbePublished 5 min read

Fetching the page
Education · Analysis
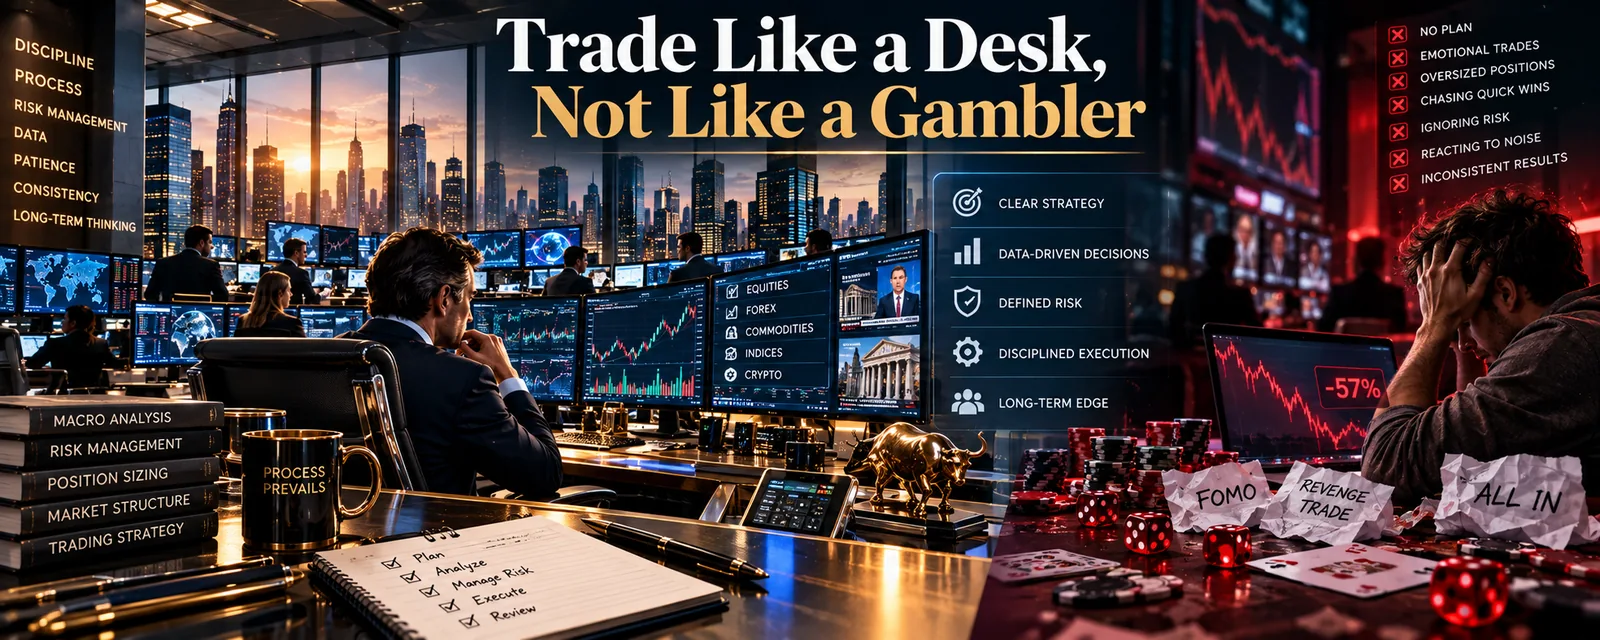
The same entry can belong to a disciplined trading business or an impulsive bet. The difference sits around the order: a mandate, a repeatable setup, a risk budget and an honest review.
Part 3 of 15Institutional Trading
@AbePublished 5 min read
A practical framework for mandates, sizing, limits and review
The same entry can belong to a disciplined trading business or an impulsive bet. The difference sits around the order: a mandate, a repeatable setup, a risk budget and an honest review.
Desk insight. Grade the decision against the plan, then assess the plan over a meaningful sample.
Gambling is not defined by the instrument. It is defined by the process. A person can gamble in government bonds and trade responsibly in volatile currencies. The question is whether the decision would look the same if it were made a thousand times.
Every institutional desk has a written description of what it may trade, in what size, and with what risk. A rates desk does not wake up and buy a biotech stock because a colleague sounded confident.
The mandate feels restrictive. It is also what creates expertise. A trader who sees the same market every day for years learns its rhythm, its participants and its traps.
The gambler has no mandate. Gold on Monday, an index on Tuesday, an exotic currency pair on Wednesday because it moved a lot. Each market is met as a stranger.
Copy this: pick two or three markets and one or two setups. Write them down. Everything else is not your business for the next six months.
Professional traders can describe their setups in plain sentences. The conditions that must be present. The entry trigger. The point at which the idea is wrong. The expected reward relative to the risk.
A written setup allows the decision to be assessed before its outcome is known. Following a tested plan is evidence of process discipline; the plan itself still needs review as results accumulate.
The gambler’s setup is a feeling. “It looked like it was going up.” A feeling cannot be tested, improved or repeated.
On a desk, position size starts from the loss the trader is allowed to take. The stop distance then gives the size. Conviction may adjust it within a narrow band.
The gambler does it backwards. Size comes from excitement, from the last result, or from how much is needed to win back yesterday. The stop is set wherever the loss becomes unbearable.
One approach is to risk a small, predefined fraction of capital per trade, with one percent or less used here as an illustration rather than a recommendation. Position size then follows from the stop distance, contract value and an allowance for costs and slippage.
Desk traders typically work within position, loss and drawdown limits. A breach triggers the firm's specified response, such as stopping new trades, reducing exposure or escalating to risk management.
These limits exist because every trader, however experienced, makes worse decisions while losing. The firm does not rely on self-control at the worst moment. It removes the decision.
The gambler’s limit is the account balance. That is the difference between a bad day and a finished career.
Copy this: set a daily loss limit, such as two or three losing trades or a fixed percentage. When it is hit, close the platform. No exceptions written in the moment.
Markets pay bad decisions often enough to be dangerous. A trader who doubles a losing position and is rescued by a reversal has learned the worst possible lesson.
Desks review trades against the plan. A loss that followed the rules is a cost of doing business. A profit that broke them is a warning.
Gamblers judge by the last result. A win proves genius and a loss proves the market is rigged. Neither produces learning.
Many profitable strategies lose on close to half their trades. Some trend strategies lose far more often and survive on a few large winners.
A desk plans around its observed win rate, average win and loss, and plausible losing streaks. Whether ten consecutive losses are ordinary or exceptional depends on the strategy and on how independent its results are.
The gambler needs each trade to win. That need produces the classic errors: moving stops, taking profits too early, and adding to losers.
Every institutional trade leaves a trail: time, price, size, reason, risk at entry. Performance is broken down by strategy, by market and by time of day.
This is where improvement comes from. A trader may find that all the profit comes from one setup in one session, and everything else is noise that feels like work.
A journal with five fields is enough to start: setup, entry reason, risk, result, and whether the rules were followed.
For a business, capital is what lets it open tomorrow. A desk that loses its capital has no product left to sell.
This changes the emotional weight of a trade. No single position is allowed to matter. The aim is to remain in business long enough for the edge to show.
The gambler treats capital as a ticket. One big win is the goal, and the stake is whatever is in the account.
Ask these before your next trade. A desk can answer all six in under a minute.
If an answer is missing, the trade needs more preparation. Waiting preserves capital, even though it may mean missing an opportunity.
Key takeaway. Trading like a desk does not need a Bloomberg terminal or a large balance. It needs a narrow mandate, a written playbook, size set by risk, limits that hold, and honest records.
None of that predicts the next candle. It makes sure you are still trading when your edge finally has room to work.
Part 3 of 15 in the series Institutional Trading. Next: How Institutional Traders Build a Position.
Independent educational commentary, not investment advice. References to firms do not imply affiliation or endorsement. Figures in examples illustrate a method, not a recommended allocation or a promised outcome. Trading leveraged products carries a high risk of loss.
 AnalysisEducationWhy Risk Managers Sometimes Have More Power Than TradersThe trader manages an opportunity; the risk function challenges whether the firm can afford it. When those judgments collide, effective governance gives risk officers the authority to reduce exposure and escalate the decision.@Abe6 min read
 AnalysisEducationHow Goldman Sachs Thinks About RiskThe first question in institutional trading is how much can be lost, how quickly, and who will act. Goldman Sachs offers a useful lens on that discipline: risk is measured, challenged and escalated throughout the life of a position.@Abe5 min read
 AnalysisEducationHow Institutional Traders Build a PositionFor a large order, entry is a sequence of decisions. Institutions often build positions in stages to manage market impact, timing uncertainty and the risk committed to an idea.@Abe6 min read
A short note from a GIO4X desk, filed under Education. It explains; it does not forecast and it does not tell you to trade. GIO4X is a broker and earns money when clients trade.
Editorial standardshttps://www.gio4x.com/intelligence/blog/trade-like-a-desk-not-like-a-gambler
Printed from gio4x.com.